
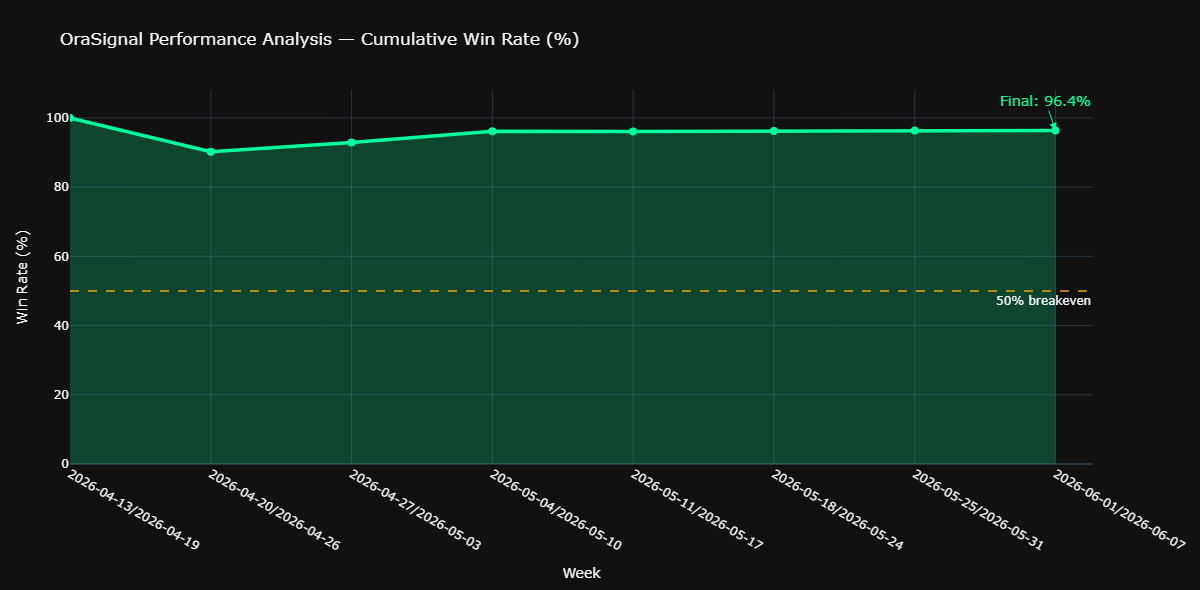
In the public domain, it is extremely difficult to find systems that simultaneously demonstrate:
-
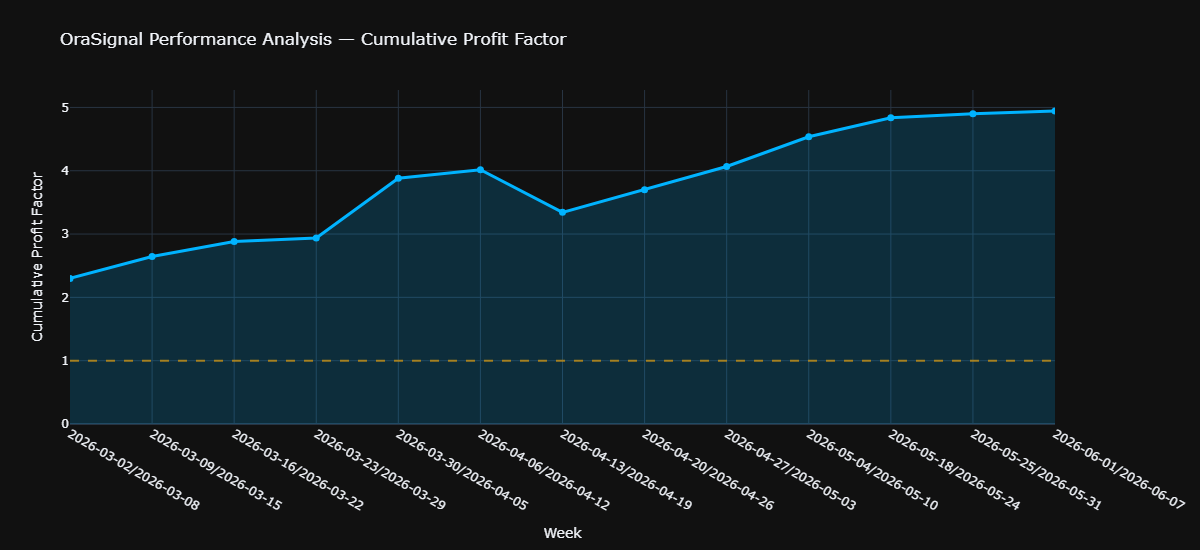
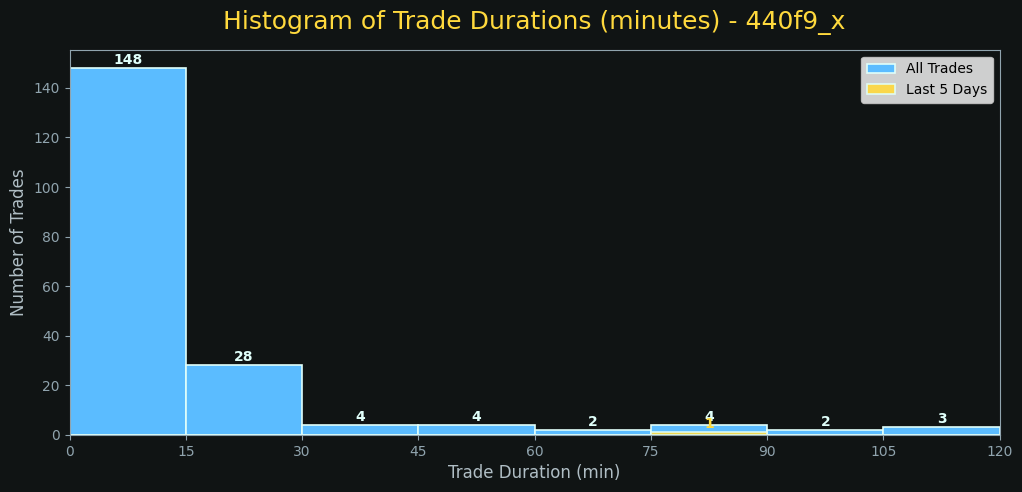
thousands of trades
-
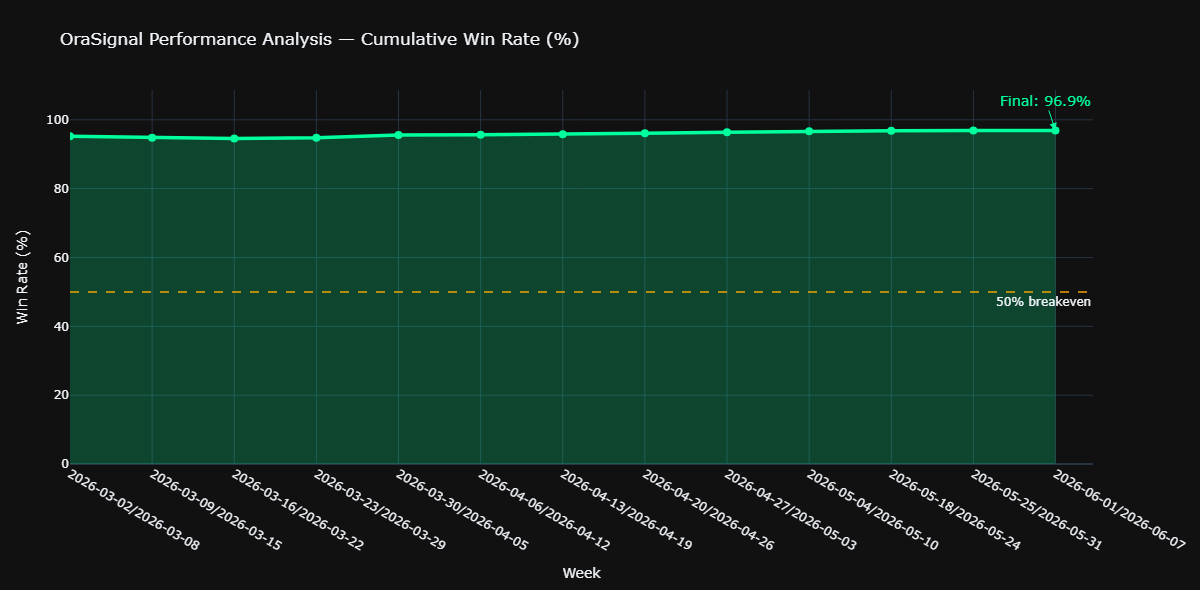
a consistently high win rate
-
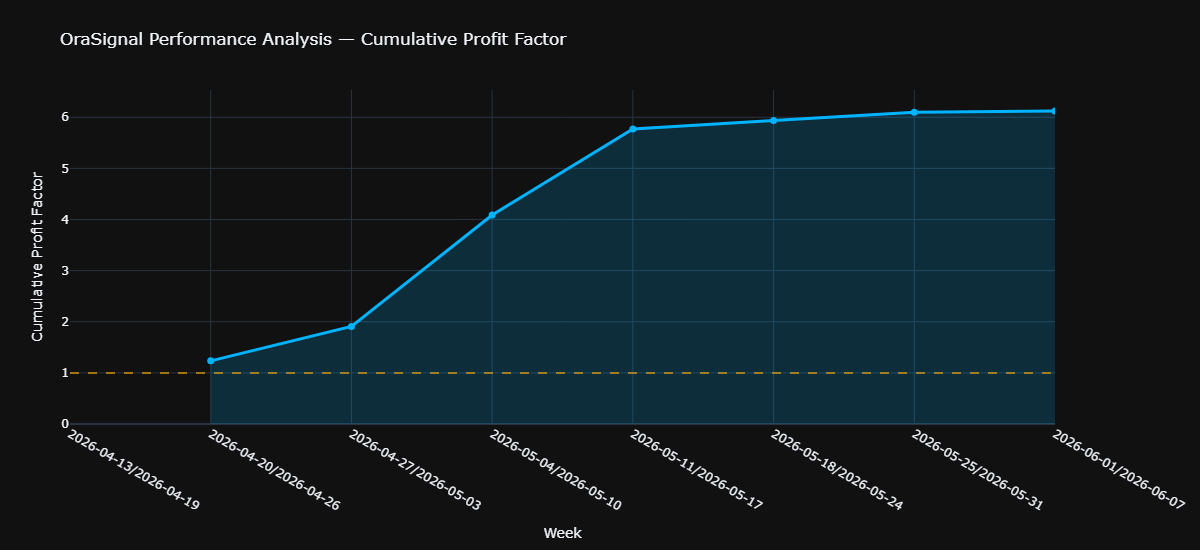
a stable profit factor
-
multi-pair trading
-
long-term operational history
ORA demonstrates all of these characteristics at once.
These are not assumptions — these are facts.

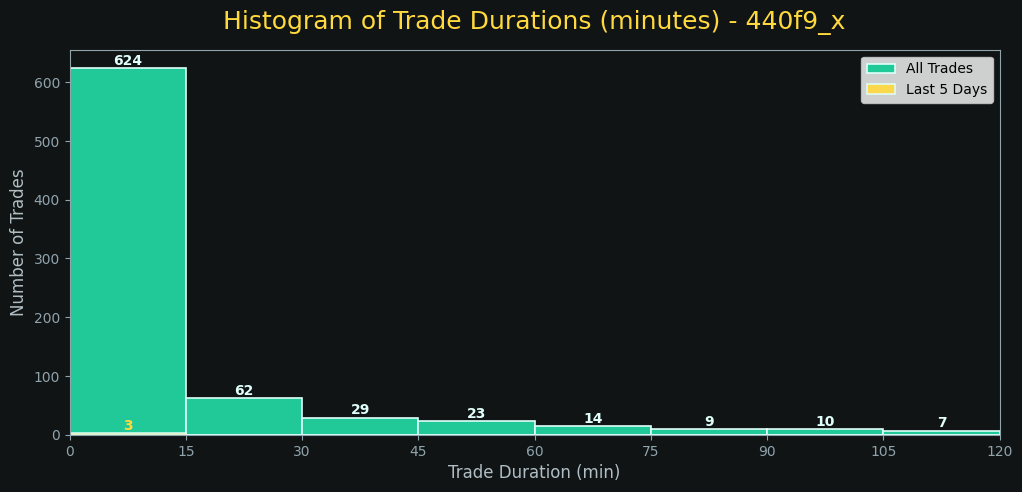

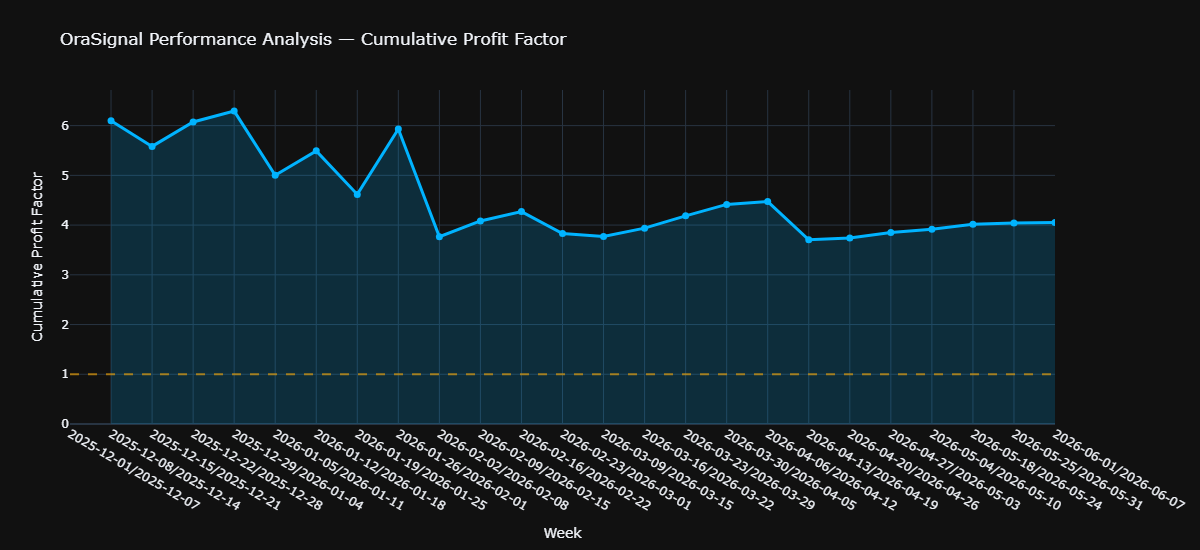

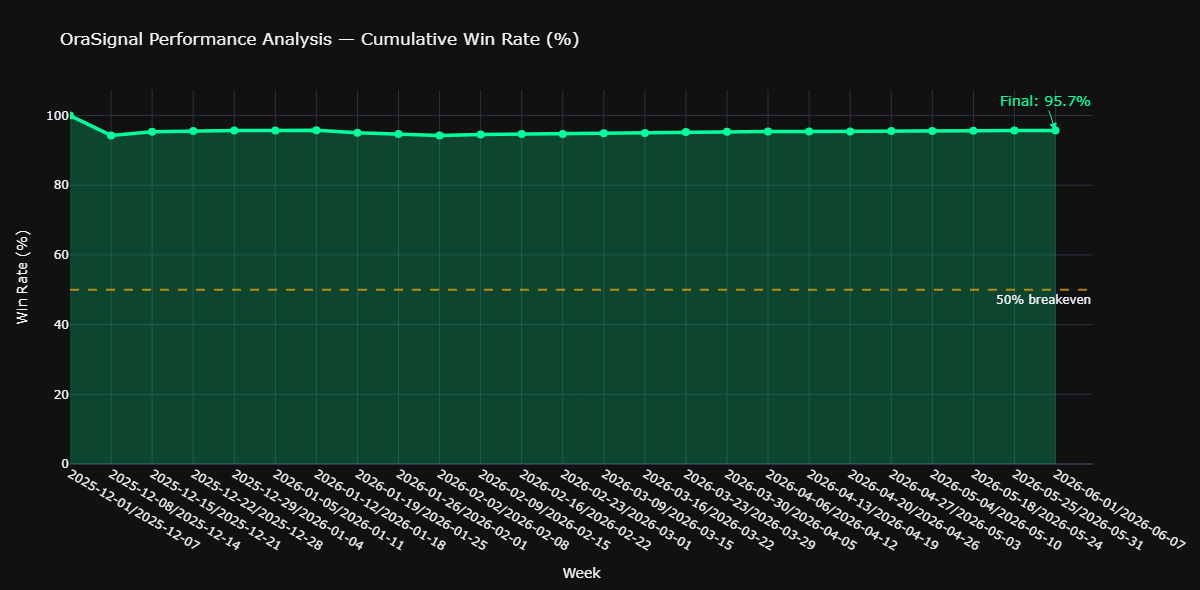

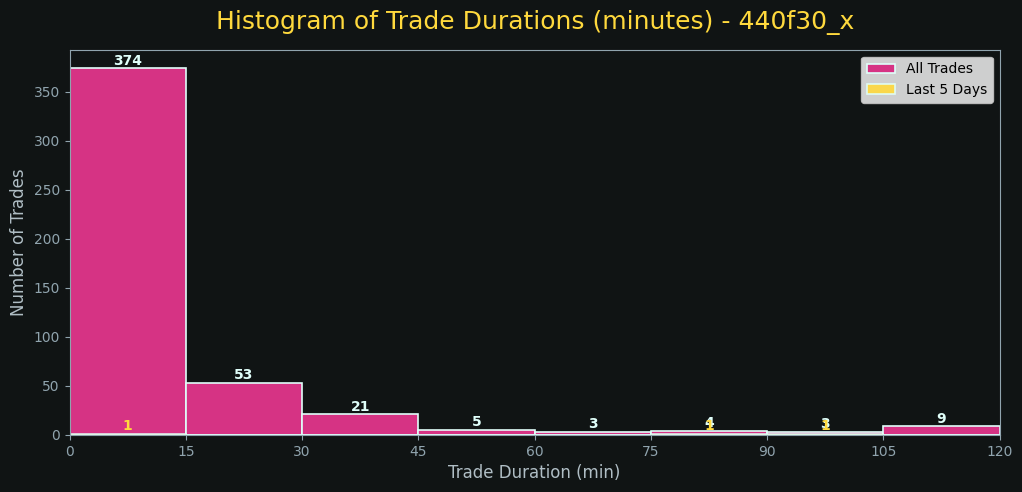





ORA is a research-oriented project focused on the analysis and modeling of price movements across currency pairs, cryptocurrencies, equities, and other financial instruments.
Our approach differs from many conventional systems in the field of automated market analysis, particularly in the way data representations and internal metrics are constructed and applied.
Initially, we did not intend to apply the metric we developed to financial market data. However, while working on unrelated mathematical and engineering problems, we identified structural properties that appeared to have potential applicability in broader stochastic environments, including financial markets.
In 2024, during research in artificial intelligence and machine learning focused on classification problems in engineering applications, we observed an unusual behavior in one of the developed metric transformations. Given its properties and our familiarity with stochastic systems in trading environments, we decided to evaluate it on financial market data.
Initial tests indicated that the metric-based system was capable of processing highly noisy and non-stationary datasets, similar in structure to those encountered in financial markets.
In certain controlled experimental settings, the system demonstrated predictive signals that exceeded baseline random performance expectations. These results are empirical observations and are subject to further validation and robustness testing.
What does this mean in practice?
