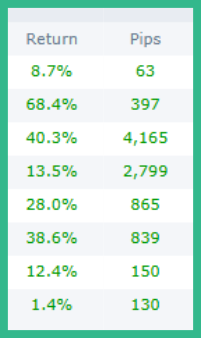
In the public domain, it is extremely difficult to find systems that simultaneously demonstrate:
-
thousands of trades
-
a consistently high win rate
-
a stable profit factor
-
multi-pair trading
-
long-term operational history
Most systems may show one or two of these characteristics.
Some may demonstrate strong results — but only over short periods or limited datasets.
Others scale in volume but lose consistency and control over time.
ORA demonstrates all of these characteristics simultaneously — within a single, continuous statistical framework.
This means we are not looking at isolated outcomes, but at a large-scale sequence of measurable and repeatable events.
These are not assumptions — these are facts, supported by verifiable trading data.
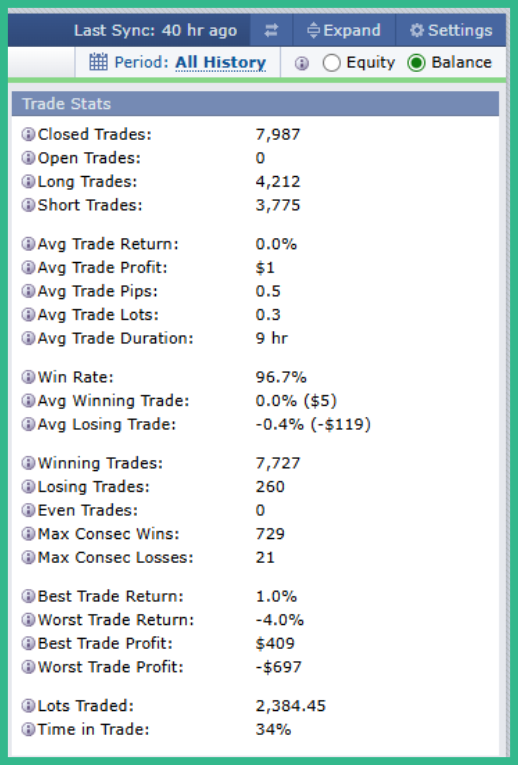
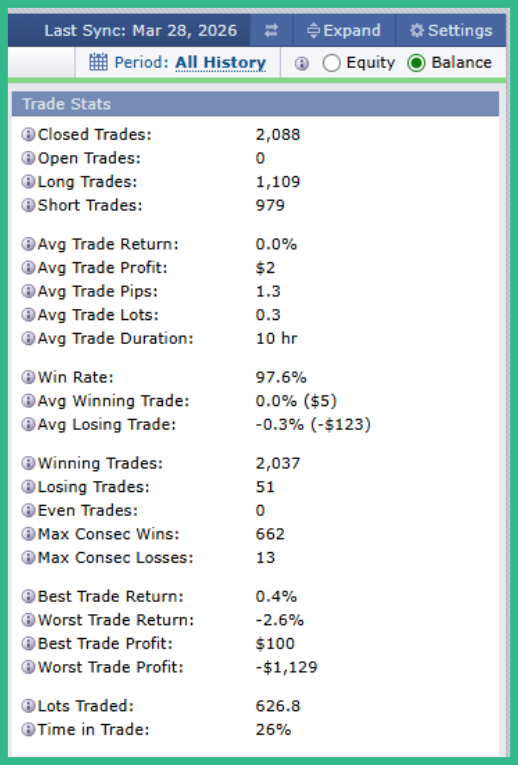
Among the publicly available ORA trading accounts, there are early-generation AI modes that most clearly confirm this.
Newer AI modes already show even stronger performance metrics. However, there will always be skepticism:
“Only 1,000 trades?”
“Only half a year?”
Which is a fair question.
That is why it is important to look at the full dataset.
Based on the earliest and longest-running configurations (over one year of operation):
- Total trades: 10,000+
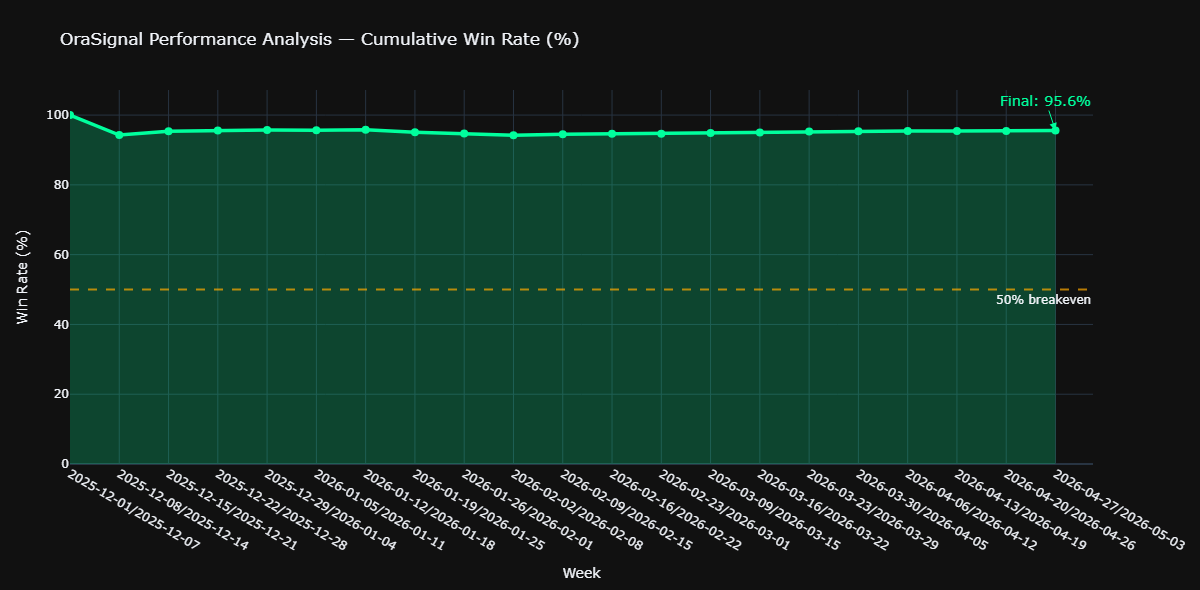
- Win rate: above 95%
- Profit Factor: above 1.5
The system operates autonomously:
- selects trading pairs (from a pool of ~20 instruments)
- operates continuously (24/5)
- determines trade direction (long/short distribution is approximately balanced)
At this scale, the market itself eliminates randomness.
When thousands of independent decisions lead to consistent outcomes, the explanation shifts from luck to structure.
In this sense, ORA’s uniqueness is not a claim — it is an observed statistical property.
Why This Is Not Random
The Concept of Event Aggregation
Any single event can be random.
But a sequence of thousands of events becomes a pattern.
In trading, almost anything can be shown once.
But almost nothing can be repeated thousands of times.
- a single result ≠ a system
- a sequence of results → an object of analysis
If these results were random, then at this scale:
- the win rate would deteriorate
- the profit factor would converge toward 1 (or below)
- the performance series would repeatedly break
- results would not remain stable over months
Conclusion: none of this is observed.
Why This Matters
For traders:
-
improved entry filtering
-
better understanding of market structure
-
reduced decision-making errors
For investors:
-
statistically grounded performance
-
scalability potential
-
repeatability of results



Final Thought
ORA is not a hypothesis.
It is an already recorded statistical reality.
The question today is no longer whether the system works.
The real question is: how can this advantage be effectively utilized?